Why Jurisdiction Still Matters Under MiCA
Choosing where to base a CASP licence isn’t just paperwork anymore — it shapes how the whole business actually runs afterward. Speed matters, sure, but so does whether the regulator picks up the phone, whether banks will actually work with you, the tax picture, how much real presence you need on the ground, and whether the structure still looks credible to investors once the licence is in hand.
MiCA was built to harmonize crypto regulation across the EU, and on paper, it does that — get authorized in one member state, and passporting lets you offer services across the entire EU and EEA without chasing separate licences country by country. But harmonized law doesn’t mean identical experiences. Every applicant still ends up dealing with its own national authority, its own supervisory culture, and a handful of practical realities — how easy banking actually is, whether decent service providers exist locally, and what the process really costs to run from start to finish. This, depending on the country, can make a MiCA licence feel like a fairly smooth process or turn into a lot of unnecessary friction, even though the underlying regulation is technically identical either way.
For founders, that means the jurisdiction choice ends up mattering well beyond the application itself. It affects whether the regulator actually gives you useful feedback before you file, how fast problems get sorted out once they come up, whether your banking setup makes sense, and whether you can grow afterward without having to tear the whole structure apart and rebuild it.
None of that comes down to tax rates or which name sounds most reputable — those metrics don’t tell you much about what actually happens once you’re mid-application. What matters more in practice is whether the national framework is genuinely in force with a clearly identified authority behind it, how the licensing process plays out in terms of timelines and regulator responsiveness, how solid the surrounding environment is once you’re licensed — banking, service providers, a functioning local ecosystem — whether substance requirements can be met without turning the business into something economically awkward, and how well the whole setup supports growth and passporting once the licence is actually in hand.
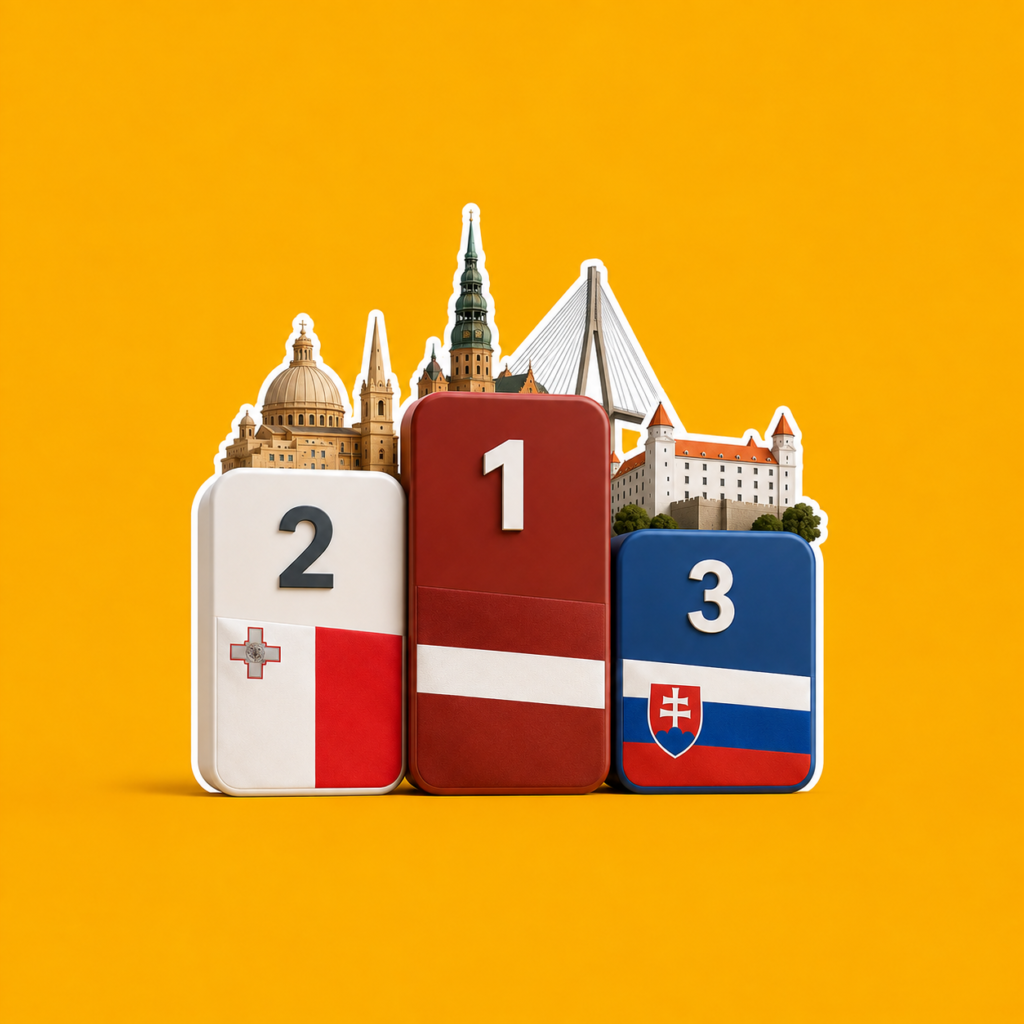
Measured against those factors, three jurisdictions stand out clearly from the rest: Latvia, Malta, and Slovakia, in that order. Latvia currently has the best combination of low cost, direct access to its supervisor, and real licensing momentum you can point to. Malta is genuinely excellent on maturity and credibility, but its more expensive structure keeps it in second. Slovakia does well on structure and cost discipline, though it falls slightly short of the other two once ecosystem depth and current momentum come into play — it tends to suit firms that want something practical and don’t mind a bit more setup work upfront.
Latvia
Latvia earns the top spot because it’s currently got the best mix of legal clarity, an active regulator, reasonable costs, and genuine practical upside. It’s moved well past the «we’re MiCA-ready» stage — at this point it’s one of the clearest examples in the EU of a country actually turning MiCA into real, granted licences rather than just a framework on paper.
Part of that comes down to timing. Latvia’s Law on Crypto-asset Services came into force on 30 June 2024, Latvijas Banka was named the competent authority, and CASP authorization rules kicked in from 30 December 2024. For anyone applying, that removes a lot of the guesswork — the framework exists, the supervisor is known, and getting licensed isn’t some theoretical future step anymore.
Having a single supervisor helps too. Latvijas Banka handles CASP oversight entirely on its own, which means one point of contact throughout both the authorization process and everything that comes after. That tends to make things more predictable — there’s no risk of getting conflicting signals from different bodies handling different pieces of the review.
But the strongest evidence is just how much Latvijas Banka has actually been licensing. By July 2026, it had granted CASP authorization to ten different companies, and it wasn’t a slow trickle — four firms got licensed in June 2026 alone. That’s not a regulator dabbling in crypto policy as a side project; that’s an authority that’s actively built a real track record.
What’s licensed matters as much as how many. Paybis picked up both a MiCA CASP licence and a PSD2 payment institution licence from Latvijas Banka in May 2026 — the first time the central bank had issued that particular combination together. Nodu followed with the same dual approval in July, becoming the tenth company licensed under MiCA since the framework took effect. Those aren’t small approvals — they signal that Latvia is comfortable overseeing firms that blend crypto services with regulated fiat infrastructure, which happens to be exactly the kind of model a lot of exchanges, wallet providers, and payment-linked crypto businesses are trying to build right now.
Then there’s cost, which is honestly one of Latvia’s biggest selling points. The application fee for CASP authorization is EUR 2,500 — the lowest anywhere in the EU — and annual supervision runs at 0.6% of gross revenue with a EUR 3,000 floor. For a scaling firm watching every euro of advisory and setup spend, that’s a genuinely accessible entry point compared to what some other jurisdictions charge just to get in the door.
The process itself is built to be workable too, not just technically compliant. Applicants get free consultations with Latvijas Banka’s own experts before they even submit anything formally, plus access to an Innovation Hub for working through questions early. Once filed, there’s a 25-working-day completeness check followed by a 40-working-day substantive review — and well-prepared applications have reportedly gone from start to finish in roughly three to six months. Those timelines obviously depend on how clean the application is, but the pattern is clear: this isn’t a regulator waiting passively to be tested. It’s actively pushing applications through.
Put all of that together, and Latvia becomes an especially strong pick for growth-stage CASPs specifically. It offers something that’s genuinely hard to find combined in one place — a regulator that’s serious and engaged, a legal framework that actually works, a visible track record of approvals, and application costs that don’t immediately push you into a bloated, expensive setup just to get licensed.
What Makes Latvia Work Strategically
The first real strength here is proportionality. Latvia is demanding enough to stay credible, but it doesn’t tip into the kind of burden that only massive institutions could realistically absorb. That balance actually matters under MiCA — jurisdictions that are too light on requirements raise reputational red flags, and ones that are too heavy make licensing technically possible but commercially painful.
The second strength is what it signals to everyone else in the room. When a regulator has already approved a meaningful number of CASPs — and shown it’s willing to license more complex combinations like crypto-plus-payments models — applicants get to walk into conversations with investors and banking partners pointing at real precedent instead of theoretical process. That makes the whole licensing plan a lot easier to defend internally.
The third is just how accessible the process is before you ever file anything formal. Free consultations, the Innovation Hub, a clearly mapped-out sequence of stages — all of that cuts down uncertainty well before submission. For compliance teams, that translates into real time saved and less risk of getting blindsided by objections halfway through.
Who Latvia Actually Suits
Latvia makes the most sense for firms that want to enter the EU through a regulator that’s active, centralized, and clearly paying attention to the sector. That’s especially true for exchanges, brokers, custodial platforms, and crypto-fiat hybrids that might eventually need both CASP authorization and complementary licences like a payment institution approval down the line.
It also fits firms that want cost discipline without settling for a jurisdiction that looks cheap or low-credibility. Latvia’s fees are genuinely accessible, but supervision still runs through the central bank under a functioning statutory framework — not some light-touch registration scheme. That combination is really the whole reason Latvia currently looks like the strongest all-around entry point into the EU’s MiCA landscape.
Malta
Malta lands in second place because it’s playing a fundamentally different game than Latvia — it’s not chasing volume or fresh momentum, it’s leaning on eight years of supervisory experience that predates MiCA entirely. Malta was the first EU country to regulate crypto comprehensively, doing it through the Virtual Financial Assets Act back in 2018, long before MiCA existed as a concept anywhere in the bloc. That framework was formally repealed in July 2026 once Malta’s transition to MiCA completed, with the new Malta MiCA Act (Chapter 647) now anchoring the domestic crypto framework — but the eight years of supervisory experience built under VFAA didn’t disappear with the old law. That head start is really the whole story here: MFSA isn’t learning how to supervise crypto businesses on the fly the way some newer regulators are.
Part of what makes that history valuable is how it’s changed the behavior of everyone else around the regulator. Banks that have dealt with Malta’s VFA regime over the years are noticeably more comfortable with crypto business models than banks in jurisdictions where this is all still new territory. That familiarity tends to make onboarding faster and considerably less painful — firms aren’t spending months explaining basic concepts to compliance teams who’ve never seen a crypto client before. Institutional investors read the situation the same way. An eight-year track record of balancing innovation against investor protection carries real weight in due diligence conversations, in a way a framework that only went live a year or two ago simply can’t replicate yet, no matter how well-designed it is on paper.
The licensing structure itself follows the same three-tier system used across the EU under MiCA — Class 1 at EUR 50,000 for advisory, portfolio management, and order-flow services, Class 2 at EUR 125,000 for exchange and custody activity, and Class 3 at EUR 150,000 for firms planning to operate a full trading platform. Where Malta actually pulls ahead of a lot of the field is timeline predictability. Well-prepared applications typically move from formal submission to approval in six to nine months, and MFSA has kept authorizing growth-stage and mid-sized firms throughout that window rather than reserving licences almost exclusively for the largest institutional players. In several other EU jurisdictions, that same process can stretch well past a year, sometimes without much clarity on where things actually stand along the way.
Tax treatment is where Malta genuinely separates itself from the rest of the field, and it’s arguably the single biggest reason firms keep choosing it despite the higher entry cost elsewhere. The headline corporate rate sits at 35%, which sounds high until you factor in Malta’s shareholder refund mechanism, which brings the effective rate down to roughly 5% once profits actually get distributed to shareholders. That sits alongside 0% withholding tax on dividends paid to non-resident shareholders, VAT exemptions on crypto token issuance and exchange activity, and a network of more than 80 double taxation treaties. For a firm building an international structure that needs to move money across borders efficiently, that combination is genuinely difficult to replicate anywhere else in the EU.
None of that comes free, though, and Malta doesn’t pretend otherwise. Substance requirements are mandatory and specific — a real physical office and local key personnel, not just a registered address on a letterhead — and the overall cost of getting set up and running tends to sit meaningfully higher than in Latvia or Slovakia. Legal fees alone typically start from around EUR 30,000, and monthly operating costs for board, MLRO, and office functions run from roughly EUR 6,000 upward once the business is live. That’s really the trade-off at the center of the Malta decision: more institutional maturity, a deeper ecosystem, and a stronger tax outcome, purchased at a meaningfully higher price of entry than the other two jurisdictions on this list.
What Makes Malta Work Strategically
The first strength is the sheer depth of the surrounding ecosystem. Malta has spent years building out genuine fintech infrastructure — venture capital funds, fintech incubators, and investment managers who already understand crypto business models rather than treating them as an unfamiliar risk category. That extends to a network of pre-vetted compliance specialists, experienced fund administrators, and banking partners who don’t need the basic concept of a crypto business explained to them before a conversation can start.
The second strength is what substance actually buys founders here, beyond just satisfying a regulatory checkbox. A physical office and real local decision-making open doors with fiat banks that already understand crypto operations, and they establish credibility with MFSA from day one rather than having to be built up gradually over months of supervisory back-and-forth. That substance also supports genuinely clean EU and EEA passporting, without running into pushback from host-country regulators who might otherwise question whether a Malta-based licence reflects a real operating business.
The third strength is regulatory precedent that applicants can actually point to. MFSA’s continued willingness to license growth-stage and mid-sized firms, not just the largest institutional players with unlimited compliance budgets, means smaller applicants aren’t walking into a process effectively designed to filter them out. That’s a meaningful difference from jurisdictions where the regulatory bar quietly assumes a certain scale of operation before it even opens the door.
Who Malta Actually Suits
Malta makes the most sense for firms that value deep institutional credibility and a mature, fully built-out operating ecosystem over securing the lowest possible entry cost. It’s a particularly strong fit for businesses planning genuinely international structures, since the tax treatment and treaty network do real, measurable work for cross-border operations in a way that flatter, lower-cost jurisdictions generally can’t match no matter how efficient their licensing process looks on paper.
It also suits firms that are comfortable investing more upfront in exchange for a regulator with a genuinely long track record, a banking sector that’s already fluent in crypto business models, and an investor community that doesn’t need convincing that Malta-based crypto businesses are a serious, stable proposition.
Slovakia
Slovakia takes third place, and it earns that spot through structure and cost discipline rather than raw momentum or institutional polish — it’s a genuinely different value proposition from either Latvia or Malta, built around discipline rather than speed or prestige. The National Bank of Slovakia oversees CASP licensing as a single competent authority, and the country isn’t trying to build a crypto market from nothing the way some smaller EU states effectively are. It’s bringing an already-established virtual asset ecosystem into a more formal, MiCA-aligned framework, which changes the character of the whole licensing experience.
That existing familiarity matters more than it might initially seem. Slovak banks, advisors, and regulators have dealt with crypto business models for a while now, which tends to shorten the «explaining the business» phase that slows things down considerably in newer or less experienced jurisdictions. NBS also offers an optional pre-licensing meeting for applicants who are already well along in their preparation, giving firms a genuine chance to walk through their business model and intended services before the formal file goes in — rather than discovering structural objections only after formal submission, when they’re far more expensive to fix.
Where Slovakia really differentiates itself from the rest of the field is on substance, and this is worth understanding in some detail because it shapes almost everything else about the jurisdiction. NBS applies what amounts to a genuinely strict substance test — a real registered office, physical premises actually available for on-site supervision, and key personnel physically based in Slovakia handling risk management, compliance, and strategic decision-making. Letter-box structures, pure passporting shells, and reliance on a virtual office with no actual staff are explicitly rejected as a matter of policy, not just discouraged informally. That’s a meaningfully tougher bar than some other EU jurisdictions set in practice, but it also means a Slovak licence carries genuine operational weight rather than functioning as just a formal stamp of approval with little behind it.
The numbers back up Slovakia’s reputation as the practical, cost-aware option in this comparison. Corporate income tax runs on a tiered scale — 10% on taxable income up to EUR 100,000, 21% on income between EUR 100,000 and EUR 5 million, and 24% above that threshold — which keeps the overall tax structure predictable and genuinely easy to plan around for a real operating business rather than a purely theoretical one. The statutory review period runs up to 40 working days once a file is formally declared complete, though in practice, well-prepared applications tend to run three to nine months from initial submission through to final decision. Office, salary, and administrative costs also tend to run noticeably lower than in Western European jurisdictions, which matters considerably for firms actually planning to staff a genuine local presence rather than just satisfying a substance requirement on paper.
Slovakia is also getting ahead of a compliance requirement that most other jurisdictions are still catching up on. DAC8 and CARF reporting take effect from January 2026, and Slovakia transposed DAC8 into national law back in 2024 — giving firms real, meaningful lead time to build proper reporting systems before the deadline actually lands, rather than scrambling to retrofit compliance under deadline pressure the way firms in slower-moving jurisdictions may end up doing. That lead time is a genuine structural advantage, not just a minor procedural footnote, because reporting infrastructure built from the ground up tends to work far better than infrastructure bolted on after the fact.
What Makes Slovakia Work Strategically
The first strength is cost efficiency without sacrificing regulatory seriousness in the process. Slovakia manages to be noticeably cheaper to operate in day-to-day than Western European alternatives while still applying a substance test tough enough to keep the resulting licence genuinely credible with banks and counterparties, rather than trading cost for credibility the way some lighter-touch jurisdictions effectively do.
The second strength is the ecosystem that already exists on the ground. Because Slovakia already has meaningful history with virtual asset activity, banks and service providers aren’t approaching crypto clients as some unfamiliar novelty requiring extensive internal education. That existing familiarity tends to translate directly into fewer delays during banking onboarding, which is often the single biggest practical bottleneck firms encounter after licensing in less experienced jurisdictions.
The third strength is regulatory clarity heading into the future rather than just in the present moment. The early transposition of DAC8 and the lead time built into the broader CARF rollout mean Slovak CASPs can design their reporting systems properly and thoroughly from the outset, instead of retrofitting compliance under real deadline pressure the way firms in jurisdictions that moved more slowly on implementation may eventually have to.
Who Slovakia Actually Suits
Slovakia is the better fit for firms that want a genuinely operational EU base rather than a jurisdiction chosen mainly for brand recognition or the lowest possible headline licensing fee. It suits businesses that are willing to build real local substance — actual staff, an actual office, actual decision-making happening on the ground — in exchange for meaningfully lower ongoing operating costs and a regulator that already understands the sector rather than treating each new applicant as an educational exercise.
It’s also a sensible option for firms that prioritize predictable, tiered taxation and early compliance readiness on DAC8 and CARF over the higher-touch, higher-cost ecosystem that Malta offers, or the lower entry barriers that make Latvia the more accessible starting point for firms earlier in their growth trajectory.
Sources:
EU-Level (ESMA)
Latvijas Banka
MFSA
-
MFSA Circular to the Industry on the Authorisation Process for MiCA Applicants, official PDF
-
MFSA Markets in Crypto-Assets Rulebook (official regulatory text)
-
MFSA Financial Services Register (for verifying which firms actually hold current licences)
-
Chapter 647, Markets in Crypto-Assets Act, official Malta legislation portal